Immediate Annuity (SPIA) Explained
By Hans Goldstein, EA, founder, Retirement Literacy Foundation · Updated
Admitted to practice before the IRS.
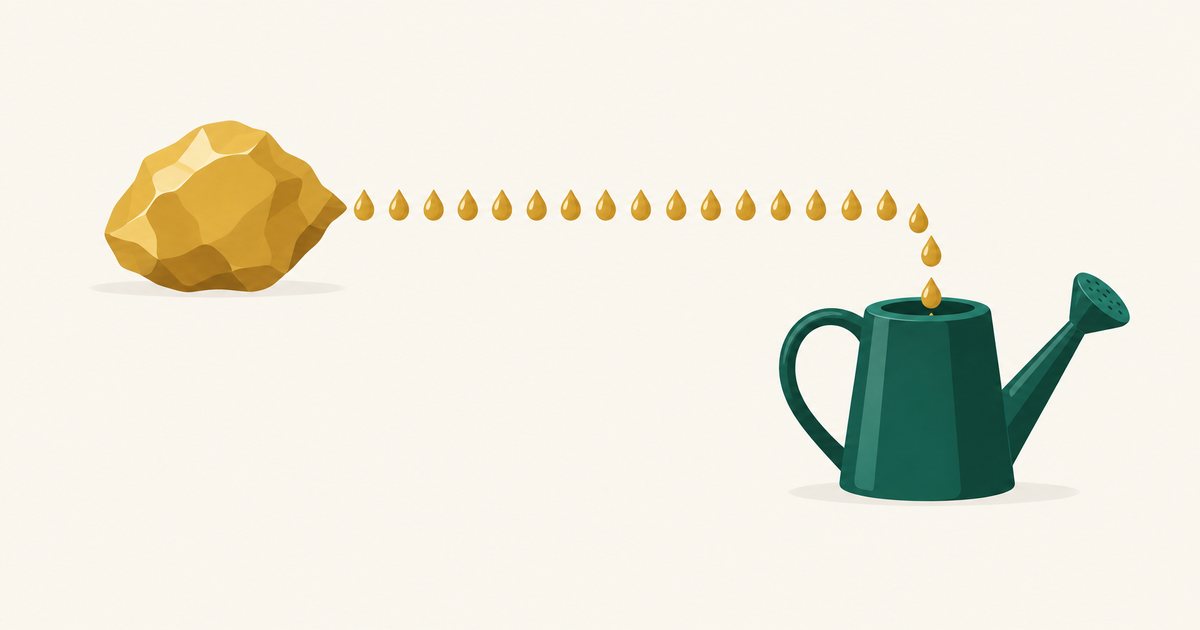
Payout options
- Life only: the highest payment, ending at death.
- Life with period certain: pays for life, and to a beneficiary for the rest of a guaranteed period (for example 10 years) if you die early.
- Cash or installment refund: guarantees at least your premium back, to you or your heirs.
- Joint and survivor: pays for as long as either spouse lives, often at a lower amount.
- Period certain only: pays for a set number of years.
What decides the payment
Your age (older buyers get more per dollar), the payout option, interest rates when you buy, and sometimes your health. More guarantees for heirs mean a smaller check. Some contracts add a cost-of-living increase, which starts the payment lower.
Get the free Social Security guide.
If “Immediate Annuity (SPIA) Explained” was useful, the same plain-English treatment of Social Security is yours free. It covers the taxable-benefit thresholds, the survivor-benefit trap and the claiming-age math. We’ll also let you know when the next free class is. Nothing to buy.
The Retirement Literacy Foundation is a 501(c)(3) public charity (EIN 41-5062266). This is free public education. We don’t sell financial products and we don’t give individualized advice. We’ll email it to you. Unsubscribe any time.
Trade-offs
- Usually irrevocable: little or no access to the lump sum after the free-look period.
- Fixed payments lose buying power to inflation unless you add an increase.
- Life-only income stops at death.
- The upside: income you cannot outlive, and it is often used to cover basic bills alongside Social Security.
Taxes
In a non-qualified SPIA, each payment is part tax-free return of your premium and part taxable interest, using the exclusion ratio, until your premium is recovered (IRS Publication 939, December 2025). Inside an IRA, payments are fully taxable and can satisfy RMDs. Payments from an immediate annuity are an exception to the 10% early withdrawal tax (IRS Publication 575, 2025). See how annuities are taxed.
Common questions
How much does a $100,000 annuity pay per month?
It depends on your age, sex in some states, the payout option and interest rates on the day you buy. Older buyers and life-only options get the highest payments. To compare offers fairly, look at dollars per month for the same payout option.
Can I get my money back from an immediate annuity?
Usually not after the free-look period, unless you chose a refund or period certain option, which pays the remainder to your beneficiaries.
Is a SPIA the same as a pension?
It works much like one: a lump sum converted into guaranteed monthly income for life. See pension lump sum vs annuity.
Sources (checked October 10, 2026): IRS Publication 939, December 2025 (exclusion ratio); IRS Publication 575, 2025; SEC Investor.gov, annuities.
Related
- Pension lump sum vs annuity
- Annuities in an IRA and QLACs
- Annuity types, pros and cons
- Turn a 401(k) into monthly income
- All annuity education pages
More on annuities: How Do Annuities Work? A Plain-English Guide · How Are Annuities Taxed? · Inherited Annuity Taxes · 1035 Exchange · Annuities in an IRA · Annuity Surrender Charges and How to Get Out of an Annuity · Types of Annuities and Their Pros and Cons · What Is a MYGA? Multi-Year Guaranteed Annuities Explained · Fixed Index Annuity Explained · Variable Annuity Explained · Annuity vs CD
Education only; nothing is sold here and no product is recommended. The Foundation's work is independent of any outside professional activity. RLF sells nothing and accepts no funding from financial companies. Tax rules depend on your situation; check with a tax professional before acting.
Want to run these numbers for your own situation?
The Retirement Literacy Foundation runs free retirement classes on Social Security timing, taxes in retirement, and how to turn savings into income. No products are sold at our classes.
Hans Goldstein, EA
Founder & Executive Director · Retirement Literacy Foundation, a 501(c)(3) non-profit
Admitted to practice before the IRS
Want more information on this? Put your name below and I’ll send it over in plain English, at no cost. If your situation has a wrinkle, reply to the email and tell me what it is; I read them.
You’re reading: Immediate Annuity (SPIA) Explained
Free education. The Foundation sells nothing. By submitting you agree to receive free educational emails. We never sell or share your information and you can unsubscribe from any email.