How Do Annuities Work? A Plain-English Guide
By Hans Goldstein, EA, founder, Retirement Literacy Foundation · Updated
Admitted to practice before the IRS.
The two phases
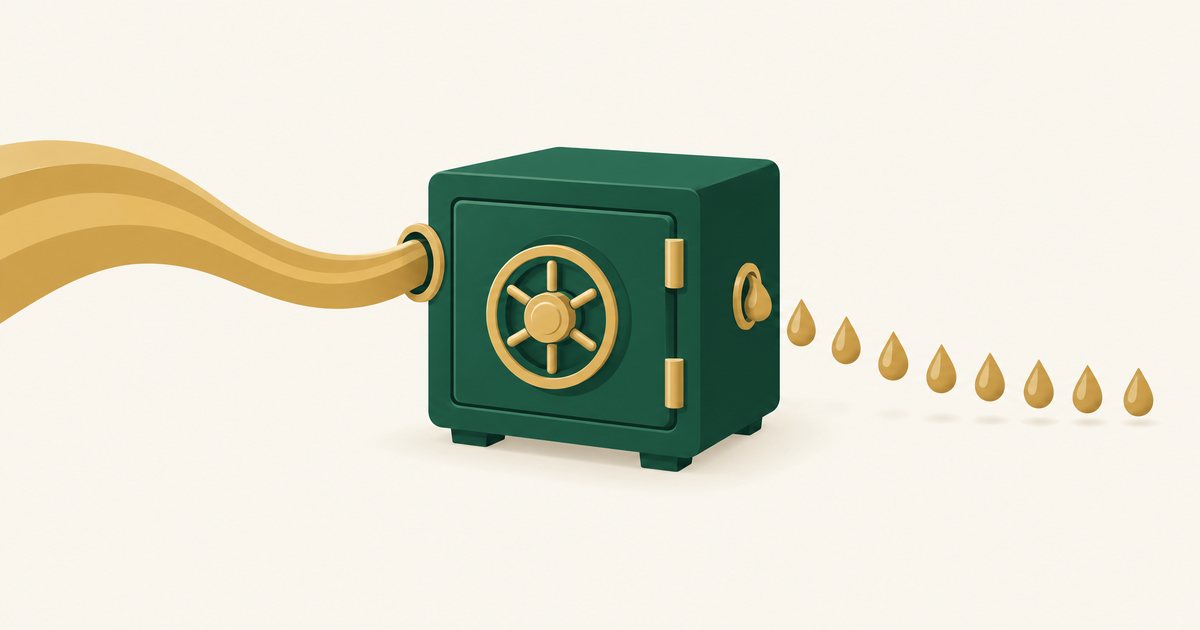
Almost every annuity has two phases:
- Accumulation phase. Your money sits in the contract and earns interest or investment returns. You do not pay tax on the growth while it stays inside (this is the tax deferral).
- Payout phase. You take money out, either as withdrawals or by annuitizing: converting the balance into guaranteed payments for a set number of years or for life. Some people never annuitize and simply withdraw or pass the contract to heirs.
An immediate annuity skips the accumulation phase: you pay a lump sum and income starts within a year. A deferred annuity grows first and pays later.
The main types
- Fixed annuity, including a multi-year guaranteed annuity (MYGA): the insurer credits a stated interest rate for a set term, often 3 to 10 years. It behaves a lot like a CD issued by an insurance company instead of a bank.
- Fixed indexed annuity (FIA): interest is linked to a market index such as the S&P 500, subject to a cap, participation rate or spread, with a 0% floor so the credited value does not drop when the index falls. The insurer can usually reset caps after the first term; the RLF studied how far: see the minimum-cap study.
- Variable annuity: money goes into investment sub-accounts, so the value rises and falls with the market. Fees are typically higher, and these are regulated as securities.
- Single premium immediate annuity (SPIA): a lump sum turned into income right away, for life or a set period.
- Deferred income annuity (DIA) and qualifying longevity annuity contract (QLAC): income that starts years later. A QLAC is a DIA held in an IRA or 401(k); see annuities in an IRA, RMDs and QLACs.
Get the free Social Security guide.
If “How Do Annuities Work? A Plain-English Guide” was useful, the same plain-English treatment of Social Security is yours free. It covers the taxable-benefit thresholds, the survivor-benefit trap and the claiming-age math. We’ll also let you know when the next free class is. Nothing to buy.
The Retirement Literacy Foundation is a 501(c)(3) public charity (EIN 41-5062266). This is free public education. We don’t sell financial products and we don’t give individualized advice. We’ll email it to you. Unsubscribe any time.
What you give up
- Access. Most deferred annuities charge a surrender charge if you take out more than a free amount (often 10% a year) during the first several years.
- Tax rate on gains. Growth comes out as ordinary income, not at capital gains rates. See how annuities are taxed.
- The 59½ rule. Taxable withdrawals before age 59½ generally owe an extra 10% federal tax unless an exception applies.
- Heirs. Annuities do not get a step-up in basis at death; the gain is taxable to your beneficiary. See inherited annuity taxes.
What the guarantees rest on
Annuity guarantees are backed by the issuing insurance company's ability to pay, not by the FDIC. Each state also has a guaranty association that covers annuity owners up to a limit if an insurer fails (the limit varies by state). Checking who owns the insurer and its financial strength ratings is part of understanding any contract: see who owns your insurer.
Every state also gives you a free-look period after the contract is delivered, usually 10 to 30 days, to cancel for a refund. In California it is 30 days for buyers 60 and older (California Insurance Code section 10127.10).
Common questions
Is an annuity a good idea?
It depends on what you need the money to do. Annuities can provide guaranteed income or a guaranteed rate, but they trade away some access, pay ordinary income rates on gains and do not get a step-up for heirs. The pros and cons are laid out on our types and pros and cons page.
Can you lose money in an annuity?
In a fixed or fixed indexed annuity, the credited value does not drop because of market losses, but surrender charges and some fees can reduce what you get if you leave early. A variable annuity can lose value with the market.
Are annuities FDIC insured?
No. They are backed by the issuing insurance company and, up to limits, by your state's insurance guaranty association.
Sources (checked October 10, 2026): IRS Publication 575, 2025; IRS Topic 410; SEC Investor.gov, annuities; National Organization of Life and Health Insurance Guaranty Associations (state guaranty limits).
Related
- Are annuities a good investment? An honest answer
- Questions to ask before buying an annuity
- The Fine Print: what the brochure leaves out
- How annuities are taxed
- Annuity types, pros and cons
- Surrender charges and getting out
- MYGA vs CD spread index
- All annuity education pages
More on annuities: How Are Annuities Taxed? · Inherited Annuity Taxes · 1035 Exchange · Annuities in an IRA · Annuity Surrender Charges and How to Get Out of an Annuity · Types of Annuities and Their Pros and Cons · What Is a MYGA? Multi-Year Guaranteed Annuities Explained · Fixed Index Annuity Explained · Immediate Annuity (SPIA) Explained · Variable Annuity Explained · Annuity vs CD
Education only; nothing is sold here and no product is recommended. The Foundation's work is independent of any outside professional activity. RLF sells nothing and accepts no funding from financial companies. Tax rules depend on your situation; check with a tax professional before acting.
Want to run these numbers for your own situation?
The Retirement Literacy Foundation runs free retirement classes on Social Security timing, taxes in retirement, and how to turn savings into income. No products are sold at our classes.
Hans Goldstein, EA
Founder & Executive Director · Retirement Literacy Foundation, a 501(c)(3) non-profit
Admitted to practice before the IRS
Want more information on this? Put your name below and I’ll send it over in plain English, at no cost. If your situation has a wrinkle, reply to the email and tell me what it is; I read them.
You’re reading: How Do Annuities Work? A Plain-English Guide
Free education. The Foundation sells nothing. By submitting you agree to receive free educational emails. We never sell or share your information and you can unsubscribe from any email.